South Bend Business Owners: What the New Tax Law Means for Your Business Interest Deductions
By Uncle Joe Tax Services | November 20, 2026
As we head into the heart of tax season here in South Bend, our team at Uncle Joe Tax Services has been closely reviewing the latest guidance from the IRS. If you own a business and carry debt, you’ve likely heard of the “Section 163(j) limitation”—a rule that caps how much business interest expense you can deduct in a given year.
Recently, the IRS released updated guidance (Fact Sheet 2026-14) reflecting changes made by the One, Big, Beautiful Bill Act. If your head is spinning from IRS jargon, don’t worry. We’ve broken down exactly what these updates mean for your bottom line and your 2026 tax return.
The Basics: What is the Section 163(j) Limitation?
Under normal circumstances, the IRS limits a business’s interest deduction to the sum of:
- Your business interest income;
- 30% of your Adjusted Taxable Income (ATI); and
- Floor plan financing interest (common for auto dealerships).
If your interest expense exceeds this limit, the excess isn’t lost forever—it carries forward to future years. However, calculating this limit can be complex, and it’s something every business owner with debt should be aware of.
The Good News: The “Small Business” Exemption
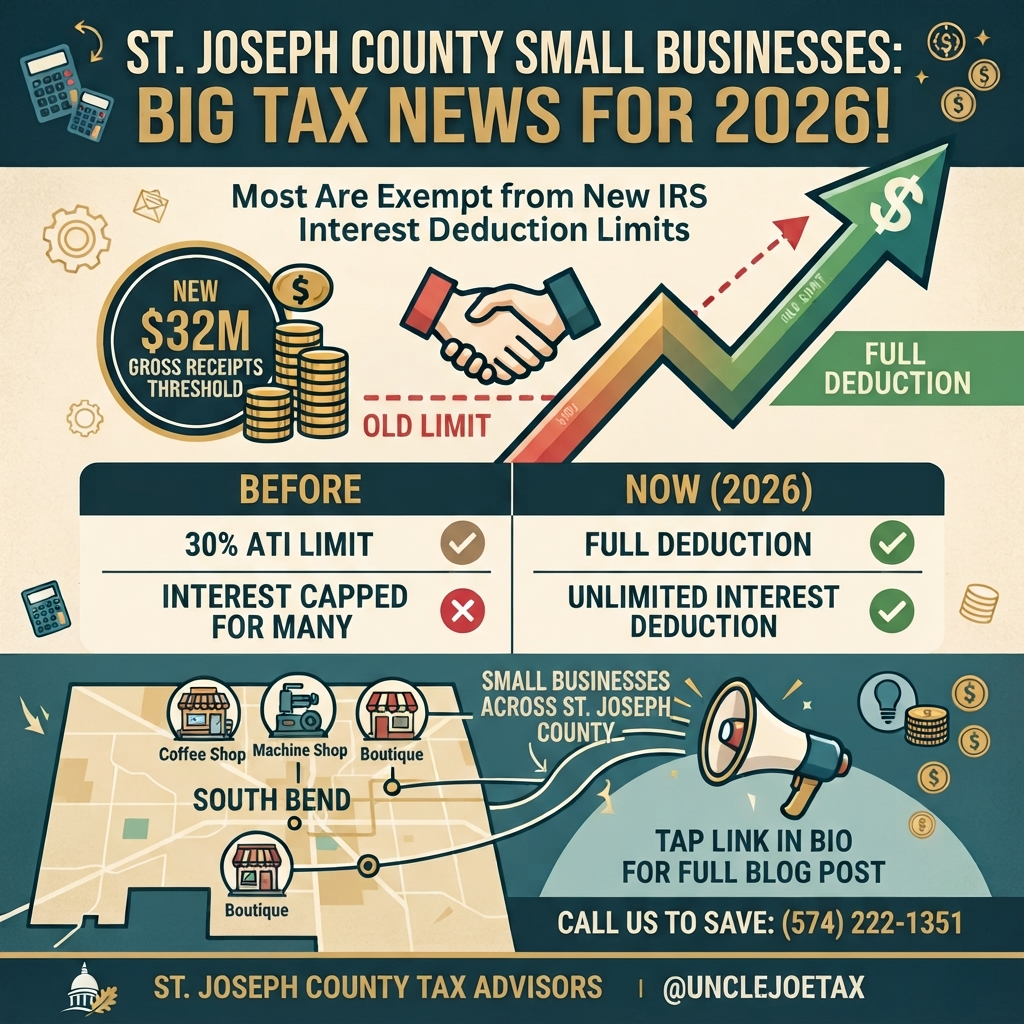
Here is the best news for our local entrepreneurs: Most small to mid-sized businesses in South Bend are completely exempt from this limitation.
You are exempt if you meet the “gross receipts test.” For the 2026 tax year, if your business has average annual gross receipts of $32 million or less over the previous three years, you do not have to worry about the Section 163(j) limitation. You can deduct your business interest expense in full.
What’s New? The One, Big, Beautiful Bill Act Updates
For those businesses that do exceed the $32 million threshold and are subject to the limitation, the recent legislative changes bring some highly favorable updates for tax years beginning after December 31, 2024:
- Depreciation Add-Back is Here to Stay: Previously, there was confusion about whether depreciation, amortization, and depletion should be added back when calculating your Adjusted Taxable Income (ATI). The new law clarifies that you must add these amounts back when calculating ATI. Because a higher ATI increases your 30% limitation cap, this change allows larger businesses to deduct more of their interest expense.
- Floor Plan Financing Expands: If you are in the business of selling or leasing motor vehicles, the definition of a “motor vehicle” for floor plan financing now explicitly includes trailers and campers designed for recreational or seasonal use.
Real Property and Farming Elections
If you operate a real property trade or a farming business, you may have previously elected to be an “excepted trade or business” to bypass the interest limitation entirely. Keep in mind that making this election comes with a trade-off: it requires you to use the Alternative Depreciation System (ADS) and disqualifies you from bonus depreciation.
With the new ATI calculations being more favorable for many, it might be time to review if this election still makes sense for your specific operation.
Let Uncle Joe Tax Services Handle the Heavy Lifting
Tax law is constantly evolving, and the difference between a generic software program and a dedicated tax professional can save your business thousands of dollars.
Whether you need to confirm if you meet the $32 million gross receipts exemption, calculate your new ATI under the One, Big, Beautiful Bill Act, or simply ensure your 2026 return is flawlessly prepared, the team at Uncle Joe Tax Services is here to help.
Ready to optimize your business taxes? Stop by our office or give us a call to schedule your consultation. Let’s make sure you are keeping more of your hard-earned money right here in the Michiana area.
📍 Visit Us: Uncle Joe Tax Services 2113 Miami Street South Bend, Indiana 46613
📞 Call Us: 574-222-1351
Disclaimer: This blog post is for informational purposes only and does not constitute official tax or legal advice. Tax laws are complex and subject to change. Please consult with a qualified tax professional regarding your specific business situation.